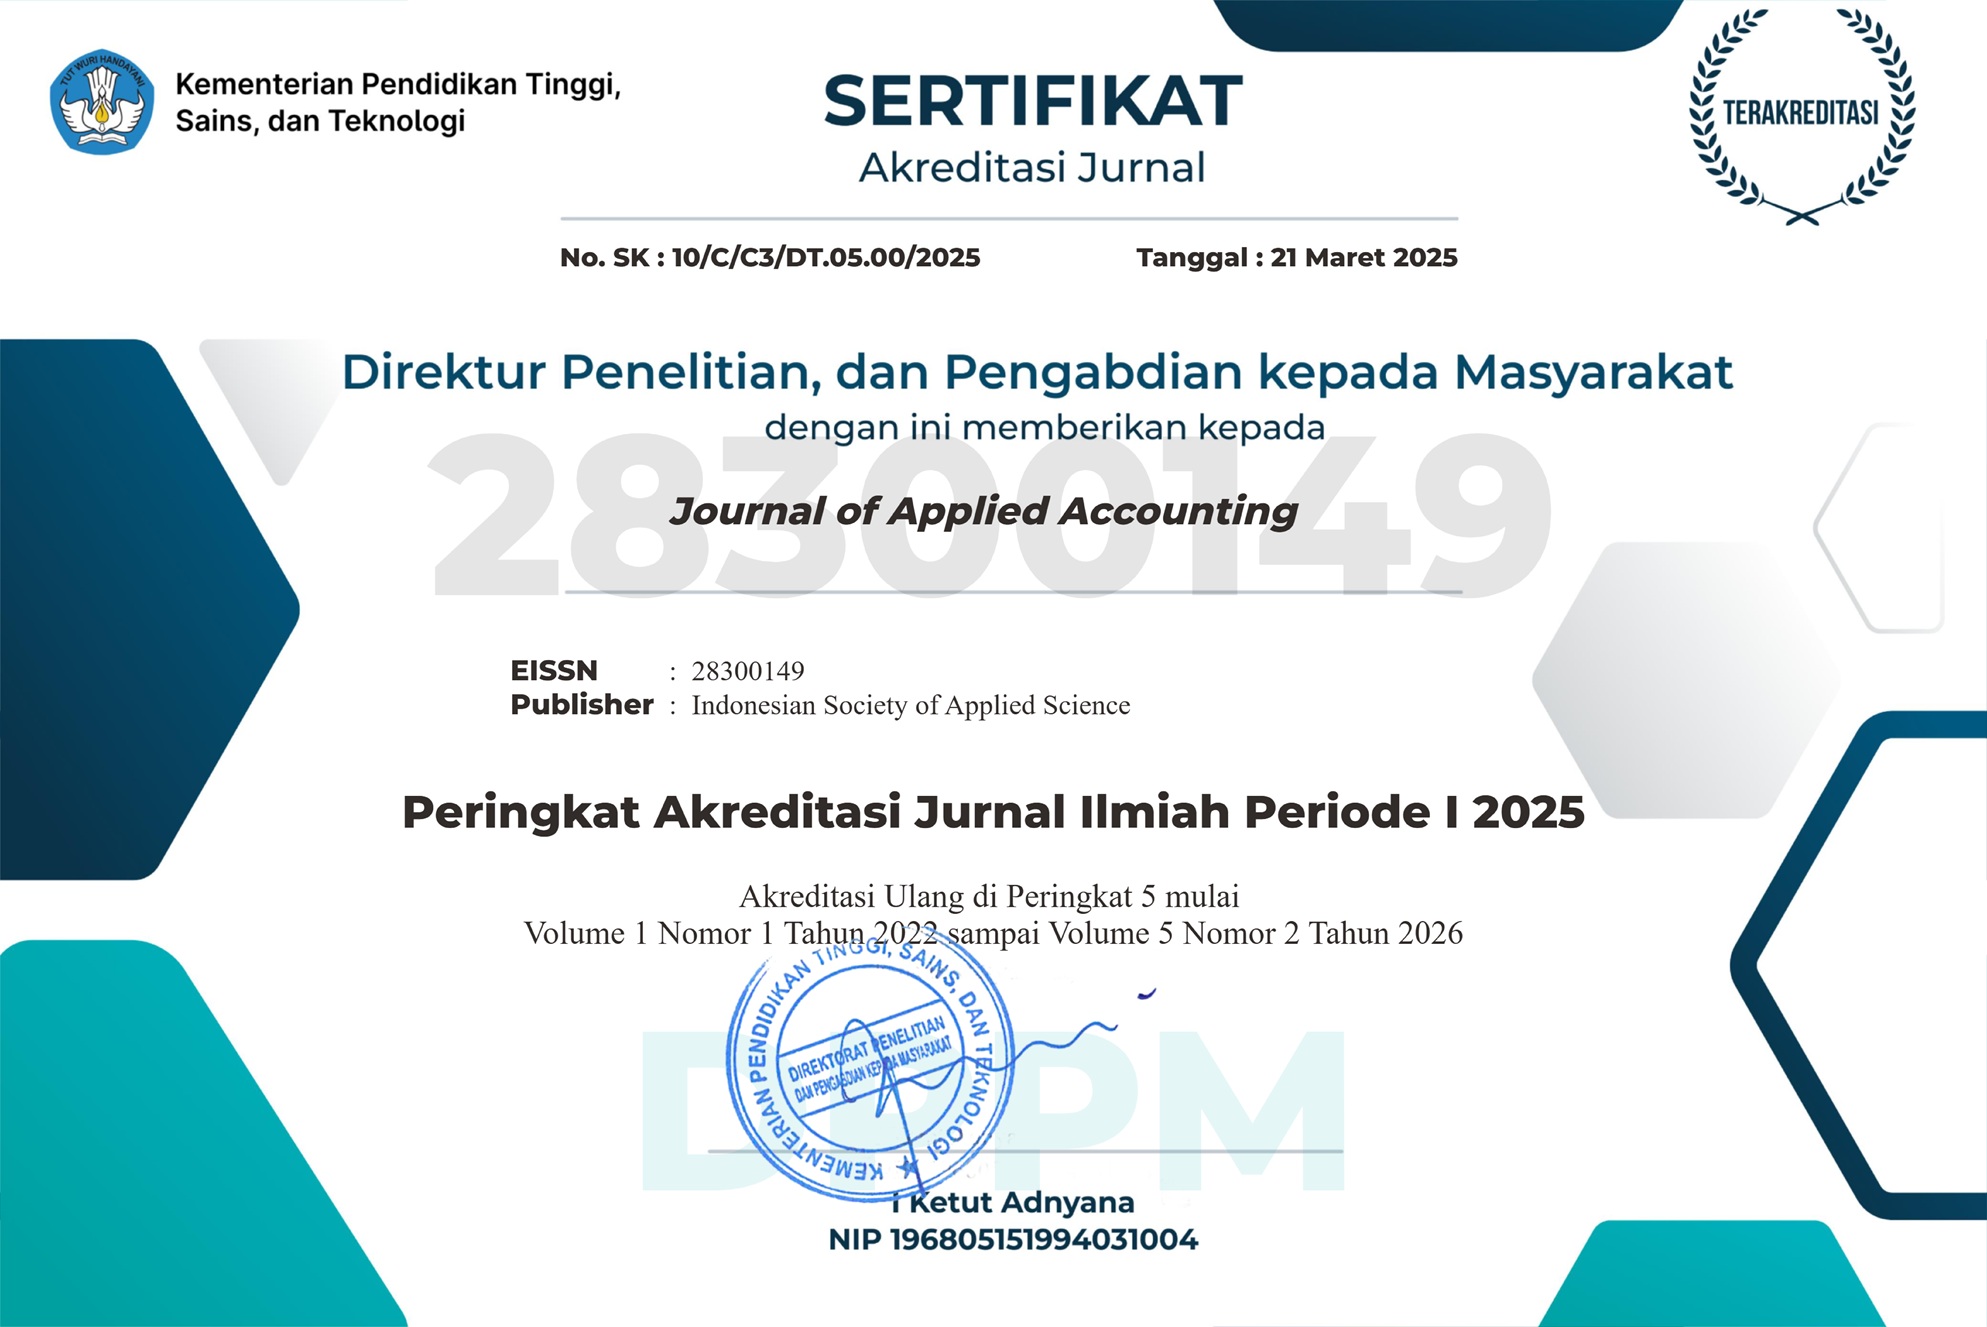
TERAKREDITASI SINTA 5
Download

TOOLS
 |
 |
 |
INDEXED BY
Review Process Policy
The Journal of Applied Accounting (JAA) applies a systematic peer-review process to ensure the quality, originality, relevance, and academic integrity of all manuscripts submitted for publication. The review process is designed to provide a fair, objective, and constructive evaluation of scholarly work in the field of accounting.
All submitted manuscripts are initially evaluated by the editor to determine their suitability for the journal's aims and scope and compliance with the required manuscript template. The editor may communicate with the authors to request clarification or revisions before deciding whether the manuscript should proceed to peer review.
Manuscripts that do not meet the journal's basic requirements or fall outside its scope may be returned to the authors or rejected at this stage.
Manuscripts that pass the initial editorial screening are sent to two reviewers for content evaluation using a blind review method. Reviewers assess the manuscript independently and provide recommendations based on their academic expertise.
The review process aims to maintain impartiality, protect the integrity of scholarly evaluation, and help authors improve the quality of their research.
Reviewers evaluate manuscripts based on the following criteria:
Following their assessment, reviewers provide constructive comments and recommendations. These may include acceptance, requests for revision, or rejection of the manuscript.
Authors may be required to revise their manuscripts in response to reviewers' comments. Revised manuscripts may be evaluated by the editor and, when necessary, returned to the reviewers for further assessment.
The editor considers the reviewers' recommendations and determines whether the manuscript meets the publication requirements of JAA. Editorial decisions are based on the manuscript's academic quality, relevance, originality, methodological rigor, and compliance with the journal's policies.
The Editor-in-Chief makes the final decision regarding acceptance or rejection of a manuscript. This decision is final.
Editors and reviewers are expected to maintain the confidentiality of submitted manuscripts and conduct their evaluations objectively and professionally. Manuscripts must not be used for personal advantage or disclosed to unauthorized parties.
Any potential conflicts of interest must be disclosed and managed appropriately to safeguard the fairness and credibility of the review process.
Through this review process, JAA seeks to publish high-quality scholarly contributions that advance accounting knowledge, improve accounting practices, and support the development of the accounting profession.
For further information, please visit the official website of the Journal of Applied Accounting (JAA):
https://journal.isas.or.id/index.php/JAA/about
|
|
|
 This Journal of Applied Accounting (JAA) is licensed under a Creative Commons Attribution 4.0 International License.