TERAKREDITASI SINTA 5
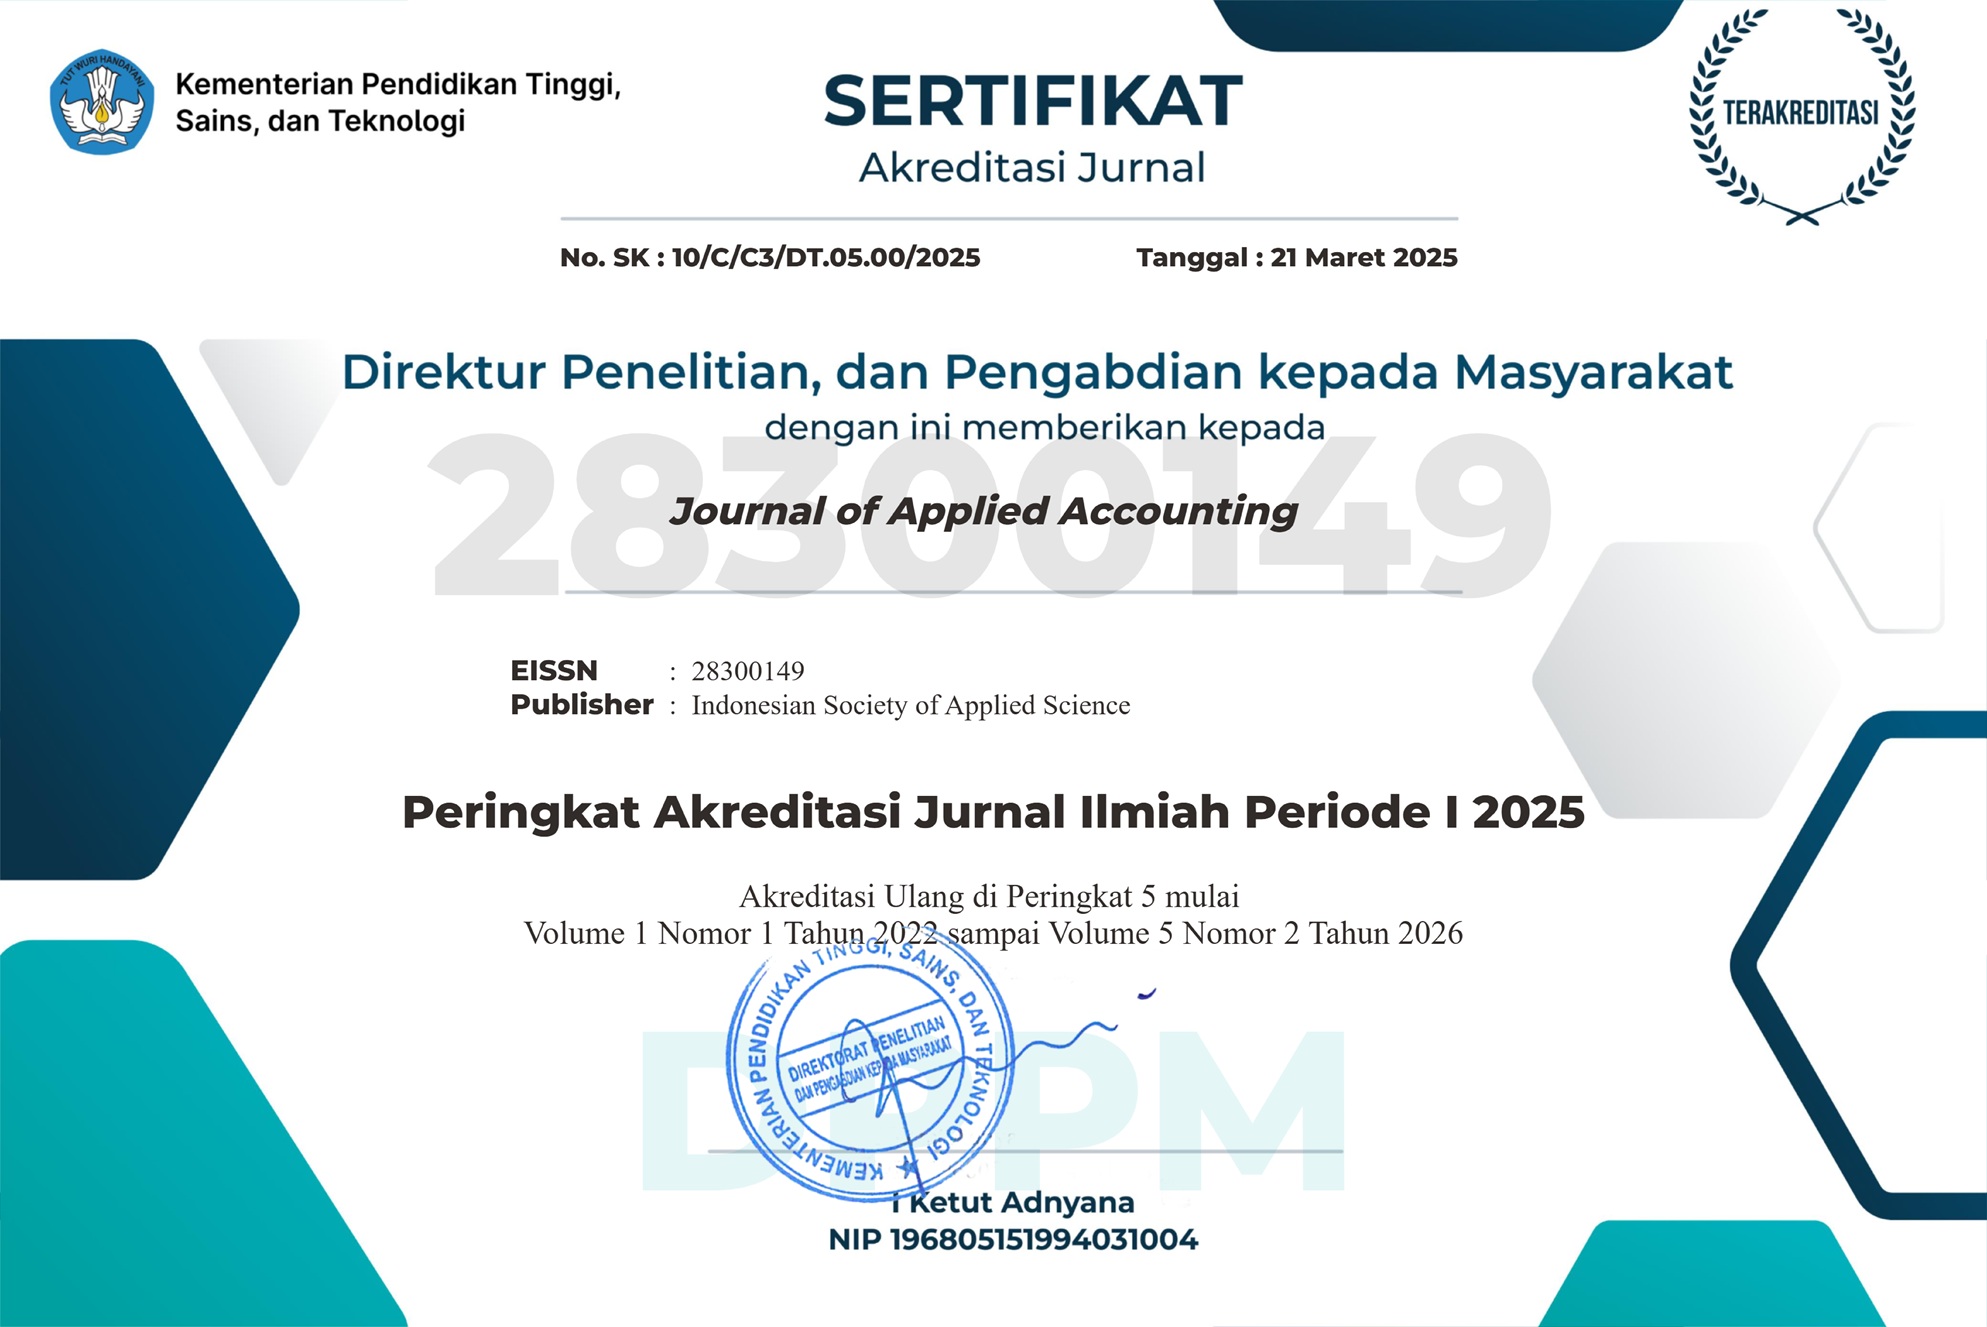
Download

TOOLS
 |
 |
 |
INDEXED BY
Objectives and Scope
Objectives
The Journal of Applied Accounting (JAA) aims to provide an academic platform for researchers, lecturers, students, accounting practitioners, and policymakers to disseminate research findings and scholarly contributions in the field of accounting. The journal seeks to advance accounting knowledge, improve accounting practices, and support the development of the accounting profession through the publication of high-quality, original, and relevant research.
JAA also aims to encourage innovation in accounting methods, promote the application of accounting theories to practical problems, and facilitate the exchange of knowledge between academics and practitioners. Through these objectives, the journal contributes to the development of transparent, accountable, and effective financial management in both public and private organizations.
Scope
The Journal of Applied Accounting (JAA) welcomes original research articles, empirical studies, conceptual papers, and other research-based manuscripts relevant to accounting theory, practice, and professional development. The journal covers, but is not limited to, the following areas:
JAA accepts quantitative, qualitative, mixed-methods, and Research and Development (R&D) manuscripts written in Indonesian or English. Submissions should demonstrate academic rigor, methodological appropriateness, originality, and a meaningful contribution to accounting knowledge or practice.
The journal welcomes contributions from researchers, academics, practitioners, regulators, students, and other stakeholders interested in advancing accounting research and professional practice.
|
|
|
 This Journal of Applied Accounting (JAA) is licensed under a Creative Commons Attribution 4.0 International License.